
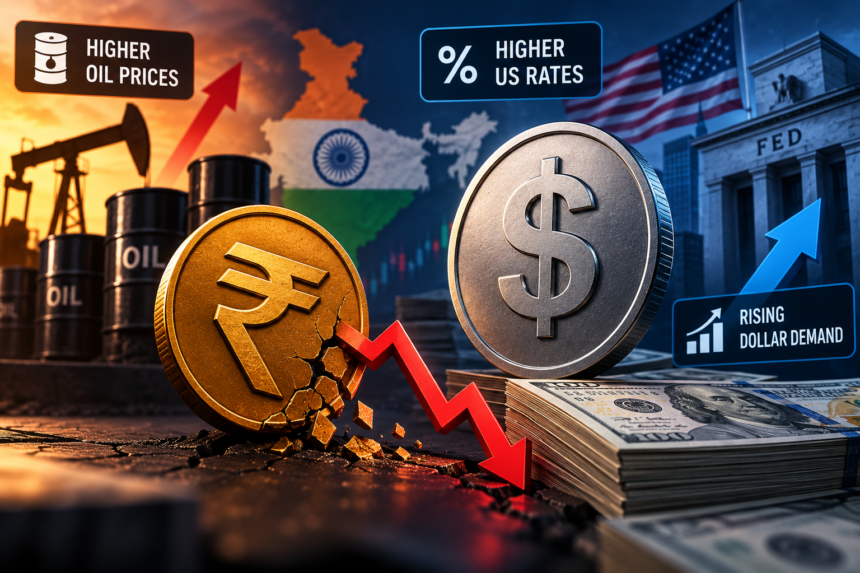
The Indian rupee has come under renewed pressure against the US dollar after briefly strengthening to a two-month high earlier this month. The currency fell past the key ₹95-per-dollar level this week and closed at ₹95.44 on September 10, its third consecutive session of decline and its sharpest single-day fall since mid-July. The latest weakness has been driven by a combination of soaring crude oil prices, escalating Middle East tensions, increased demand for dollars and concerns about global interest rates.
The decline is particularly notable because the Reserve Bank of India (RBI) had recently stepped up its intervention in the foreign-exchange market. The central bank reportedly sold at least $8 billion last week to support the rupee, helping it reach around ₹94.29 on September 3. However, renewed external pressures have made it increasingly difficult for the currency to maintain those gains.
Rising Crude Oil Prices Are the Biggest Immediate Pressure
The most important factor behind the latest rupee decline is the sharp rise in crude oil prices.
Brent crude moved above $100 a barrel this week as the conflict in the Middle East intensified, including attacks involving Iran, the United States and oil tankers in the Gulf. Brent has risen more than 6% during the week, according to Reuters, increasing concerns about India’s import bill.
India imports a large share of the crude oil it consumes. When oil becomes more expensive, Indian refiners and oil companies need more dollars to pay overseas suppliers. This increases demand for dollars in the foreign-exchange market and puts downward pressure on the rupee.
Higher oil prices can also worsen India’s trade balance. If the value of imports rises faster than exports, the country needs a larger amount of foreign currency to finance its external payments.
There is another problem: expensive oil can increase domestic inflation. That creates a difficult situation for policymakers because a weaker rupee makes imported commodities even more expensive in rupee terms.
The Economic Times reported that the rise in crude toward $100 had already offset the benefit of recent RBI intervention and pushed the rupee below ₹95.
Higher US Yields Are Supporting the Dollar
Another major factor is the changing outlook for US interest rates.
Strong US economic and employment data have increased expectations that the Federal Reserve could keep interest rates higher for longer, or even raise rates at its upcoming meeting. Markets have been closely watching inflation and employment data because stronger economic conditions reduce the urgency for the Fed to ease monetary policy.
At the same time, the 10-year US Treasury yield has been trading near multi-year highs. Higher US yields make dollar-denominated assets more attractive to global investors because investors can earn relatively higher returns by holding US government securities.
That can encourage capital to move toward the United States and away from emerging-market assets, putting pressure on currencies such as the rupee.
Reuters reported earlier this month that expectations of a Fed rate hike had pushed US yields higher and kept the dollar broadly supported.
The upcoming US inflation data is therefore particularly important. A hotter-than-expected inflation reading could strengthen expectations of tighter US monetary policy and potentially put additional pressure on emerging-market currencies.
Strong Dollar Demand From Importers and Companies
The rupee is also being affected by domestic demand for dollars.
Indian importers have increased dollar purchases and hedging activity as businesses try to protect themselves against the possibility of further rupee depreciation. Oil companies are particularly important participants in the dollar market because they require large amounts of foreign currency to pay for crude imports.
Reuters reported that persistent concerns about rupee weakness have caused hedging flows to remain tilted toward dollars, with importers increasing forward purchases while some exporters have delayed selling their dollar earnings in expectation of better exchange rates.
This creates a self-reinforcing pressure on the currency. If businesses expect the rupee to weaken, they may buy dollars earlier, increasing immediate dollar demand and adding further downward pressure on the rupee.
Derivative-market maturities have also contributed to recent dollar demand, according to Reuters.
Foreign Investor Outflows Are Adding More Pressure
The weakness in Indian equities has also become a factor.
Indian stocks have faced selling pressure as global investors react to higher oil prices, rising bond yields and geopolitical uncertainty. On September 9, the Sensex fell more than 800 points as Brent crude moved above $100, while the rupee weakened to around ₹95.10.
When foreign investors sell Indian equities and repatriate the proceeds, they typically need to convert rupees into dollars. That increases dollar demand and can weigh on the Indian currency.
Foreign portfolio flows therefore become particularly important when several negative factors occur simultaneously: weaker stocks, expensive oil and higher US yields.
Why the RBI Cannot Completely Stop the Rupee’s Decline
The RBI has substantial foreign-exchange reserves and has actively intervened to reduce excessive volatility.
India’s reserves have reached record levels, giving the central bank significant firepower to sell dollars when the rupee comes under pressure. The RBI reportedly sold at least $8 billion during the previous week, while state-owned banks were again seen selling dollars this week, likely on the central bank’s behalf.
However, intervention does not eliminate the underlying economic pressures.
If oil continues rising and companies continue buying dollars, the RBI would have to repeatedly sell foreign currency to defend the rupee. The central bank therefore appears more focused on preventing an excessively rapid or disorderly depreciation rather than maintaining a particular exchange rate indefinitely.
Interestingly, the RBI is currently dealing with the opposite problem in the banking system: excess rupee liquidity.
Huge foreign-currency inflows from overseas deposits and other policy measures have generated substantial rupee liquidity after being swapped with the RBI. Reuters estimates the banking system’s core liquidity surplus may have reached ₹14–15 trillion. The RBI has consequently been using instruments including dollar-rupee sell-buy swaps to absorb some of that excess cash.
This illustrates how complicated the current currency environment has become: the RBI has enormous foreign-exchange resources, but it is simultaneously managing surplus rupee liquidity and significant future foreign-exchange obligations.
The $136 Billion Inflow Is Helping, But It Has Limits
India recently attracted around $136.4 billion through special measures involving FCNR deposits, external commercial borrowings and overseas foreign-currency borrowings. These inflows strengthened the RBI’s ability to support the rupee and contributed to the currency’s move toward ₹94.29 earlier this month.
However, the inflows are not a permanent solution.
Some of these funds ultimately create future foreign-currency obligations, while the RBI’s forward dollar position has also increased. Reuters reported that the central bank’s net forward dollar liabilities were already around $137 billion at the end of July.
As a result, analysts expect the RBI to use these additional dollars strategically rather than simply allowing the rupee to appreciate sharply.
What Happens Next for the Rupee?
The near-term outlook will depend heavily on three variables: crude oil prices, US interest-rate expectations and geopolitical developments in the Middle East.
If oil prices remain above $100, India’s import bill could stay elevated and keep the rupee under pressure. If US inflation remains high and the Federal Reserve maintains a hawkish stance, higher Treasury yields could provide additional support to the dollar.
On the other hand, a decline in oil prices, softer US inflation or renewed foreign investment into Indian assets could ease pressure on the rupee.
For now, the latest depreciation is not being caused by a single weakness in India’s economy. Instead, it reflects a combination of expensive oil, geopolitical risk, higher US yields, dollar demand, foreign-investor flows and market expectations.
The RBI has considerable reserves and has demonstrated its willingness to intervene, but its objective is likely to smooth excessive volatility rather than permanently prevent the rupee from responding to global economic forces. With Brent above $100 and major central-bank decisions approaching, the rupee is likely to remain volatile in the near term.
About The Author